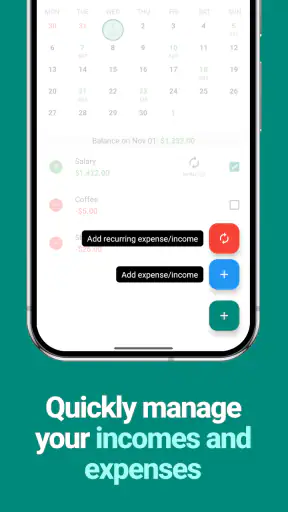
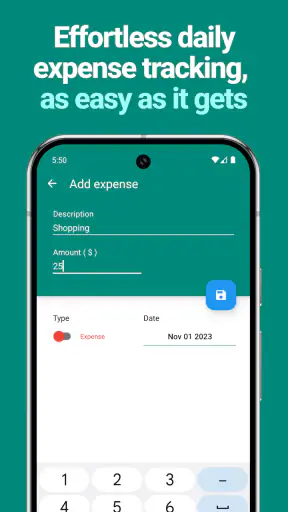
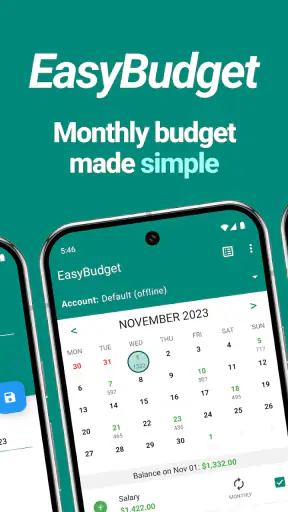
I like budget apps that get out of the way quickly. When I open a finance tool, I usually want to record a purchase, see what remains for the month, and move on with my day. EasyBudget takes that straightforward approach. It is a free budgeting app from Wallet Passes Alliance, aimed at people who want a simple monthly plan rather than a complicated personal-finance dashboard.
After spending time with it, my impression is clear: this is most useful when you already know your regular income and expenses but need a lightweight place to keep them visible. It does not try to turn budgeting into a full financial command center. That restraint is its main appeal, although it also explains why users looking for deep account connections, investment tracking, or advanced reporting may outgrow it.
How EasyBudget feels in everyday use
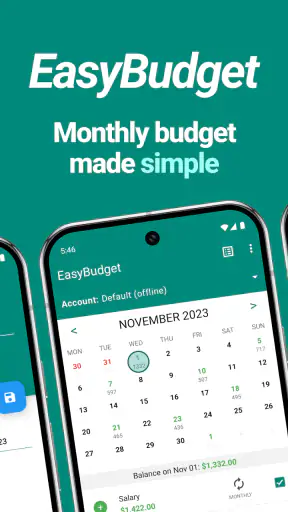
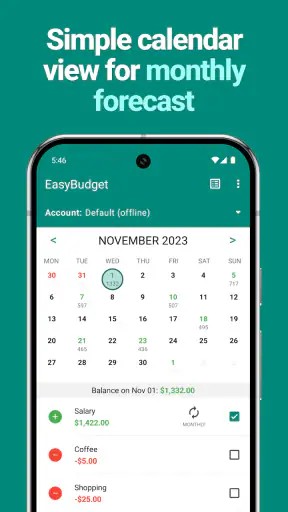
The app sits in the finance category, but its personality is closer to a digital spending notebook than to a bank replacement. I found that distinction important. Instead of asking me to understand a large system of financial categories, it encourages a monthly view: decide what money is available, account for planned costs, and check the remaining room before spending.
That makes it a natural fit for someone starting a first budget, managing a household allowance, or trying to stop relying on mental arithmetic. The interface is easier to appreciate when used frequently in short sessions. A quick entry after buying groceries is more useful than opening it once every few weeks and trying to reconstruct an entire month from memory.
The best results come from treating the app as a habit rather than as an automatic financial analyst. I would record purchases as close to the transaction as possible, keep category names understandable, and review the month several times instead of waiting until payday. The simpler the personal routine, the more helpful the app becomes.
That simplicity also means the quality of the result depends on what I enter. If I forget cash purchases or postpone several entries, the remaining budget becomes less trustworthy. This is not a flaw unique to EasyBudget, but the app’s deliberately hands-on style makes the trade-off especially visible.
A realistic monthly routine
Imagine receiving a salary and immediately separating the money needed for rent, utilities, transport, food, and flexible spending. I would enter those planned amounts first, then use the app during the month to log smaller purchases. If I notice that restaurant spending is consuming too much of the flexible amount, I can adjust the next few days rather than discovering the problem after the money is gone.
The useful moment is not the final monthly review. It is the decision made halfway through the month: cooking at home, delaying a nonessential purchase, or protecting money for an upcoming bill. EasyBudget works well in that space because it keeps the budget understandable enough to consult without turning every decision into a spreadsheet exercise.
A less obvious tip is to create categories based on decisions you actually make, not on an ideal accounting system. “Weekend spending” may be more actionable for one person than several narrow entertainment labels. The app becomes easier to maintain when each category answers a practical question: how much can I spend here before I need to slow down?
What the current version tells me
The current release is version 4.1.0, and the product has been available since December 2, 2015. That long presence suggests a tool that has had time to settle into its basic purpose rather than chasing every trend in personal finance. I see that as a positive for users who value familiarity and a focused workflow.
At the same time, an established app can feel conservative beside newer finance products. People accustomed to automatic transaction imports, elaborate charts, shared household workspaces, or synchronized accounts may find EasyBudget intentionally limited. Its identity is built around direct budget planning, so the experience is strongest when that is exactly what I need.
Wallet Passes Alliance is the developer behind the app. The product has reached over half a million installs, with an average rating of four out of five from roughly twenty-one thousand ratings. Those figures indicate a substantial audience and a generally positive reception, while still leaving room for the kind of mixed experiences that a practical budgeting tool naturally produces.
For existing users, the move to version 4.1.0 is best understood as a current-state checkpoint rather than a reason to expect a completely different app. I would not install it expecting a transformation into a banking platform. I would install it expecting the same central promise: keep monthly planning manageable and reduce the friction of tracking everyday spending.
Who benefits most from the simple approach
I would recommend EasyBudget to a student learning to divide limited income, a freelancer who wants a basic monthly spending frame, or anyone who has tried elaborate finance apps and abandoned them because setup became a project. It is also sensible for a person who prefers entering figures manually and wants the budget itself to remain the main focus.
Families can use the same idea informally, especially when one person maintains the plan and discusses the available amounts with others. The app may help make a conversation about spending concrete: instead of saying “we should spend less,” I can point to the amount reserved for a particular part of the month and decide what to change.
It is less suitable for someone who wants a complete record of net worth, recurring investments, credit-card statements, or multiple financial institutions in one place. A spreadsheet may be better for a household that needs custom formulas and detailed historical analysis. An automated finance service may be better for someone who will not consistently enter transactions by hand.
That distinction matters because a free app can still cost time. EasyBudget has no purchase price, but manual organization is the real commitment. If I know I dislike recording purchases, I should choose a system that reduces that work rather than assuming a simpler screen will solve the habit problem.
Small workflow choices that improve the experience
One practical method is to plan fixed costs before flexible ones. I would enter obligations that are difficult to change, then calculate what remains for food, transport, leisure, and unexpected needs. This prevents a pleasant-looking spending allowance from hiding bills that have not yet been accounted for.
Another useful approach is to leave a deliberate cushion instead of assigning every unit of income to a category. A budget that uses every last amount can look precise but become fragile after one irregular expense. EasyBudget is more useful when the plan reflects real life, where small surprises are normal.
I also prefer reviewing categories by frequency, not only by total. A series of small purchases can be harder to notice than one large payment. Looking at the pattern encourages better decisions: perhaps the issue is not one expensive event, but repeated convenience spending that feels harmless individually.
For irregular income, I would build the month around a conservative amount rather than the most optimistic estimate. When more money arrives, it can be assigned later. This keeps the plan from promising spending room that may not actually exist. The app can support that discipline, but it cannot decide which income estimate is responsible.
Where the app still feels limited
The main limitation is the same quality that makes EasyBudget approachable: it does not appear designed to replace every other financial tool. Users who need automatic synchronization may find manual entry slow. People who enjoy detailed visual analysis may want richer reports. Anyone managing several currencies, complex shared finances, or business bookkeeping should examine whether a more specialized product fits better.
There is also a psychological limitation. A monthly budget can encourage good decisions, but it may not explain why spending habits are changing over several months. If long-term trends are central to my goal, I would export or copy important figures into a spreadsheet or use a second tool built for deeper analysis. EasyBudget is better at keeping the present month visible than at becoming a complete financial history.
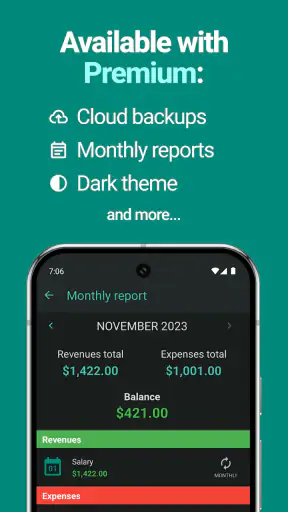
The in-app purchase range runs from ninety-nine cents to ninety-nine dollars and ninety-nine cents per item. Since the app itself is free, I would pay attention to which optional functions matter to me before spending. A person who only needs basic planning may find the free starting point sufficient, while someone considering extras should judge them against the time saved and the alternatives available.
The content rating is Everyone, which matches the app’s practical subject and broad audience. It runs on Android version 7.0 or later, so compatibility is fairly accessible for users with older supported devices. Before relying on it for an important financial routine, I would still test the exact workflow on my phone and make sure I have a personal backup method for figures I cannot afford to lose.
How it compares with familiar alternatives
Compared with a paper notebook, EasyBudget is easier to revise when a planned amount changes and more convenient to consult away from home. Compared with a spreadsheet, it should feel less demanding for quick monthly planning, although the spreadsheet wins when I want custom calculations, extensive history, or a highly personal layout.
Compared with automatic banking apps, EasyBudget gives me more intentional control over what I record, but less convenience if I expect transactions to appear without effort. That is not simply a technology difference; it changes how I pay attention. Manual entry can make purchases more noticeable, while automation can produce a more complete record with less daily friction.
Compared with envelope-style budgeting systems, the app can provide a similar sense of spending limits without requiring physical envelopes. However, people who need strict separation of funds or detailed rollover rules may prefer a dedicated envelope product. I would choose EasyBudget when clarity and speed matter more than a highly formal budgeting method.
Questions I would consider before installing
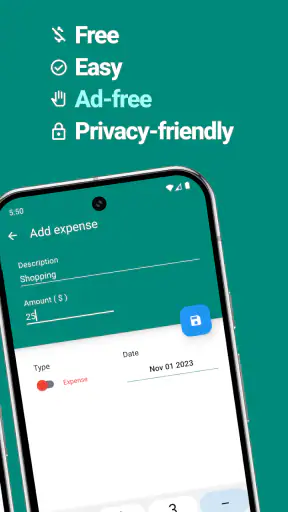
Is it genuinely free to start? Yes, the app is available at no upfront cost, which makes it easy to try with one month of real spending. I would use that trial period seriously rather than judging it after a single launch. The important test is whether I can maintain entries and understand the remaining budget without extra effort.
Is it appropriate for beginners? In my view, yes, provided the beginner is willing to enter information consistently. The simple monthly idea is less intimidating than a full finance suite. I would begin with only the categories I can explain clearly, then add detail only when a recurring problem shows that I need it.
Can it replace a bank app? I would not treat it that way. A bank app is the place to inspect accounts and transactions provided by the financial institution; EasyBudget is the place to plan how available money should be used. They can complement one another, but they serve different jobs.
Will it suit advanced budgeters? Only partly. Someone experienced may appreciate a clean planning layer, but advanced users who depend on automation, complex reporting, or broad financial tracking will probably want a more powerful companion or a different primary tool.
Is the app still worth considering with newer alternatives around? Yes, if the central need is a readable monthly plan and a low barrier to entry. The age of the product is less important than whether its focused workflow matches my habits. I would skip it only when I already know that manual budgeting is too much work or that my financial situation requires specialized features.
What I would watch as the product evolves
For future updates, I would pay attention to how the developer balances simplicity with requests for more capability. The danger is adding so many advanced controls that the monthly view becomes harder for beginners to understand. The best evolution would preserve the quick planning routine while making careful improvements for people who need more flexibility.
I would also watch how optional purchases affect the core experience. A free starting point is valuable, but users should be able to understand which parts are essential before committing money. Clear separation between basic planning and extras would help people decide without feeling that a simple budget requires a large upgrade.
Existing users should approach updates with practical expectations. Keep using the workflow that already helps, review any changed screens before a new month begins, and retain personal records for important plans. New users can start small, test one complete monthly cycle, and decide from actual use rather than from feature lists.
My final view is that EasyBudget succeeds because it respects a common truth: most people do not need a financial cockpit to make better daily choices. They need a clear reminder of what is available and a routine they can repeat. Its strongest feature is the reduction of budgeting friction, not an abundance of financial tools.
I would recommend it to anyone who wants a free, approachable monthly planner and is comfortable taking responsibility for entering spending. I would point a data-heavy user toward a spreadsheet or an automated finance service instead. For the right person, this app can turn vague intentions into a visible spending plan; for the wrong person, its hands-on nature will become the very obstacle they hoped an app would remove.


